

Wallet - Digital Card Wallet analysis by Appwee
I usually think of digital wallets as tools that promise to simplify a crowded phone, then leave me with another app to maintain. Wallet - Digital Card Wallet takes a narrower, more practical route: it puts credit cards, barcodes, and loyalty cards into one place so I can reach them without searching through a physical wallet or several separate apps. That single purpose is also its strongest argument. It is not trying to become a complete banking service; it is a card-organizing tool.
After using it, my main impression is that the value comes from reducing small interruptions. A loyalty card is useful only when I can bring it up at the checkout. A membership barcode is helpful only if I do not have to remember which retailer’s app contains it. The app turns those scattered cards into one collection, and that makes the everyday action of finding and showing a code much more direct.
The important distinction is convenience, not payment replacement. I would recommend it to someone who carries a thick stack of plastic cards or regularly forgets loyalty cards at home. I would be more cautious with anyone expecting a full financial wallet with bank transfers, account management, or sophisticated payment controls. This is a Tools app from Wallet Assistant, and its focus is clear from the way it handles cards and barcodes.
One place for the cards I actually use
The central capability is straightforward: I can gather credit cards, barcodes, and loyalty cards in a single digital wallet. That sounds modest, but it solves a very specific problem. Physical cards are easy to lose in a bag, while retailer apps often bury loyalty passes behind sign-in screens, promotional banners, or several taps. A dedicated card collection gives those items a common home.
The benefit is especially noticeable with cards I use occasionally rather than daily. I may remember that I have a cinema membership, a supermarket loyalty card, or a store barcode, but not where I put the plastic version. Instead of relying on memory, I can open the wallet and look through the cards I have saved. The app becomes a visual index for the things I would otherwise leave behind.
It also helps separate physical payment cards from cards that exist mainly for identification or rewards. Those are easy to confuse when they are all stored in a real wallet. Keeping them together digitally is convenient, but I still treat each type differently. A loyalty barcode is usually a quick scan. A credit card may still need to be physically presented or used through a payment method supported by the shop. The app’s usefulness does not automatically turn every stored card into a contactless payment instrument.
That distinction matters before installing it. I see this app as a personal organizer for card information and scannable codes, not as a replacement for a bank’s official application. If I need statements, transfers, card controls, fraud alerts, or account support, I would continue using the relevant financial service. Wallet - Digital Card Wallet is most convincing when the task is simply “show me the card I need now.”
What the single-wallet approach changes
The practical improvement is not just fewer cards in my pocket. It is fewer decisions at the moment I need one. With separate retailer apps, I have to remember the retailer, locate the app, wait for it to open, and find the membership screen. With a physical card, I have to remember which compartment holds it. A central wallet removes some of that mental sorting.
There is also a useful habit I developed: I save a card immediately after receiving it instead of waiting until I need it. That makes the wallet a prepared reference rather than an emergency filing cabinet. When I am standing at a checkout, I am not trying to photograph or organize a card under pressure. The card is already in the collection and ready to select.
For households with many memberships, this can be more valuable than it first appears. I can keep infrequently used cards available without carrying them every day. The trade-off is that the collection needs sensible organization from the beginning. If I save everything with vague names, I simply create a digital version of a messy wallet.
How I use it in practice
My first step is to add the cards I regularly need. The most useful starting point is not every card I own, but the small group that causes repeated inconvenience: the loyalty card I forget, the barcode I show at a counter, and the membership pass that normally stays in a drawer. Starting with those makes the benefit visible quickly and avoids filling the wallet with clutter.
When adding a card, I pay attention to its label. A clear name such as “weekly supermarket” or “gym membership” is more useful than leaving several similar cards indistinguishable. I also prefer names that describe the purpose rather than only the company, because I often remember what I need to do before I remember the exact card design.
Once the cards are saved, the everyday workflow is simple in concept: open the app, select the relevant card, and present the barcode or card view when required. This is where the app earns its place. It does not ask me to reconstruct my card collection at the checkout. The preparation happens earlier, and the actual use is a short retrieval task.
A small but important tip is to test saved barcodes before depending on them in a busy shop. Different scanners can be fussy about screen brightness, viewing angle, glare, and distance. If a code does not scan immediately, I would first adjust the phone’s position and brightness rather than assuming the card was saved incorrectly. This is not a flaw unique to the app; it is a reality of displaying codes from a phone screen.
I also keep the physical version of an important payment card available. A digital image or stored card entry is not the same thing as a bank-issued card, and a shop may require the original card, a supported payment terminal, or another form of verification. The safest workflow is to use the app for convenience while keeping a backup for situations where a digital display is not accepted.
A realistic checkout routine
Imagine I am buying groceries after work. I have left my loyalty card at home, and the store’s own app is not something I want to open while the queue moves. I open Wallet - Digital Card Wallet, select the supermarket card, and show the barcode. The useful part is not that the barcode has become more powerful; it is that I can reach it from the same place where I keep other cards.
That routine works best when the card has already been added and named clearly. If I am still deciding which of several nearly identical entries is the right one, the advantage disappears. This is why organizing the wallet is part of the real experience, not an optional extra. A few minutes spent cleaning labels can save repeated hesitation later.
The same approach applies to a membership card at a reception desk or a rewards barcode at a café. I do not need to carry every plastic card for the occasional situations in which those cards matter. At the same time, I would not rely on it as my only option when a card is essential for travel, access, payment, or identification. Convenience is strongest when failure would be annoying rather than serious.
Keeping the collection usable
I recommend reviewing the wallet occasionally. Cards expire, memberships change, and some loyalty programs issue replacement numbers. An outdated entry can be worse than no entry because it gives me confidence that I am showing the right thing. Removing cards I no longer use keeps the selection quicker and makes the app feel more like a useful tool than a storage box.
Another practical habit is to save only the information needed for the intended use. If a card is used for scanning, I focus on the barcode entry rather than treating the wallet as a place to reproduce every detail printed on the physical card. This keeps my routine simple and reduces the temptation to use a stored card view for a purpose it was not designed to handle.
Because the app is free to download, it is easy to try with a small set of cards before deciding whether it deserves a permanent place on my phone. The presence of in-app purchases, ranging from $9.99 to $69.99 per item, is worth noticing before committing to any paid option. I would begin with the free experience and judge whether the organization benefit is strong enough for my habits.
The people who get the most from it
The best match is someone whose physical wallet is full of cards that are used often enough to matter but not often enough to remember. That includes loyalty cards, store barcodes, club memberships, and other scannable cards. If I frequently stand at a counter thinking, “I know I have this card somewhere,” the app addresses a real annoyance.
It is also a good fit for people who move between bags, work locations, or travel light. A physical card left in yesterday’s jacket is useless today, while a saved digital version is available whenever the phone is with me. That does not remove the need for backups, but it makes occasional cards easier to carry without physically carrying them.
Families may find it useful for keeping a shared set of household loyalty cards accessible, although I would still consider who owns each account and whether the card can be used by another person. The app can organize what I have, but it cannot change a retailer’s rules about account ownership or identity checks. That is an important boundary when sharing cards.
I would skip it if I already use a reliable system that brings every relevant pass to the front quickly. Someone who keeps only one payment card and never uses loyalty programs may gain very little. I would also look elsewhere if the main requirement is banking, tap-to-pay functionality, travel documents, tickets, or detailed transaction management. Those needs belong to broader services, while this app is deliberately more focused.
Where it beats the usual alternatives
Compared with a physical wallet, the app reduces bulk and makes occasional cards easier to retrieve. Compared with separate retailer apps, it offers one place to look instead of a collection of branded destinations. That consistency is its clearest advantage. I do not have to remember which company supplied the card before I begin searching.
Compared with simply taking screenshots of barcodes, a dedicated wallet is easier to maintain as a collection. Screenshots can become mixed with photos, messages, and unrelated images, making them awkward to find. A card-specific tool gives the saved items a clearer purpose. The improvement is organizational rather than magical, but organization is exactly what I need at a checkout.
The comparison is less favorable against a full-featured operating-system wallet when the card or pass is officially supported there. A system wallet may offer faster access or deeper integration for certain payment and ticketing functions. In that situation, I would use the system option for supported items and keep this app for cards that do not fit neatly into it. The two approaches can serve different purposes rather than being mutually exclusive.
Limitations I noticed in the concept
The app depends on the quality of the cards I add and the acceptance of digital displays at the place I am visiting. A barcode that is damaged, outdated, or tied to an account requiring identity verification will not become valid simply because it is inside a wallet. I still need to understand the rules of the retailer or organization using the card.
There is also a small privacy and security trade-off whenever I consolidate sensitive cards. One app becomes a convenient central point, but that convenience means I should protect access to my phone and avoid treating the wallet as a place for information I do not need to store. I would be selective about what I add, especially when a card contains details that should remain private.
The app’s broad compatibility is appealing, but a general card organizer may not provide the same specialized experience as an official retailer app. An official app can connect directly to account balances, offers, receipts, or membership updates. Wallet - Digital Card Wallet is better when I want quick access to a card, not when I want the entire customer relationship in one place.
Its age rating is Everyone, which fits the simple organizing purpose, and it supports devices running Android 7.0 or later. The current version is 6.2.5, so users on older phones should check compatibility before planning a migration from a physical wallet. The app has been available since August 10, 2023, and its scale suggests that the basic idea has found a sizable audience: it has passed one million installs and holds a 4.7 average from around twenty-three thousand ratings.
Those figures make me more comfortable treating it as an established option rather than an experiment, but they do not remove the need to test it against personal routines. A high average rating cannot tell me whether my local scanner accepts a particular barcode or whether I prefer the app’s method of organizing cards. The real test is whether I can retrieve my most-used card faster than I can find the physical one.
My recommendation after using it
Wallet - Digital Card Wallet succeeds because it concentrates on one repeated annoyance: having a card somewhere, but not having it available when needed. The app from Wallet Assistant is free to start, simple enough for everyday use, and particularly helpful for loyalty cards and barcodes that would otherwise be scattered across a physical wallet, screenshots, and retailer applications.
I would install it gradually rather than importing everything at once. Add the cards that cause the most friction, give them clear names, and test them at home or during a low-pressure visit. Keep essential physical cards as backups, and remember that a stored card entry does not automatically replace an official banking or payment service.
My final view is positive, with a clear condition: this is a focused organizer, not an all-purpose financial platform. If your problem is card clutter and forgotten barcodes, the single-wallet approach can make ordinary errands noticeably smoother. If your priority is account management, integrated payments, or official membership features, another solution may be a better center for your digital life. For the right user, though, Wallet - Digital Card Wallet earns its place by making the small moment of finding a card almost effortless.
Gallery
Wallet - Digital Card Wallet Pros and Cons
- Keeps loyalty cards organized in one convenient digital wallet.
- Quickly displays card barcodes at checkout.
- Reduces the need to carry bulky physical cards.
- Supports easy access to cards when traveling or shopping.
- Helps prevent cards from being lost or damaged.
- Some stores may not accept digital barcodes from the app.
- Requires a charged phone to access cards when needed.
- Card compatibility can vary between retailers and regions.
- Barcode scanning may fail under poor screen brightness or glare.
- Privacy depends on how securely your device and account are protected.
Wallet - Digital Card Wallet Frequently Asked Questions
What is Wallet - Digital Card Wallet used for?
Wallet - Digital Card Wallet is designed to keep digital versions of cards and passes in one convenient place. Depending on the supported card types and your device, you may be able to organize loyalty cards, membership cards, tickets, coupons, or other scannable items. It can reduce the need to carry physical cards, although the exact features may vary by region, device, and app version.
Is Wallet - Digital Card Wallet safe to use for storing cards?
The app is intended to make digital card management more convenient, but users should still review its privacy and security practices before adding sensitive information. Avoid storing confidential data unless the app clearly supports it and provides suitable protection. Use a strong device passcode, keep your operating system updated, and check the app permissions so you understand what information it can access.
Can I add any physical card to Wallet - Digital Card Wallet?
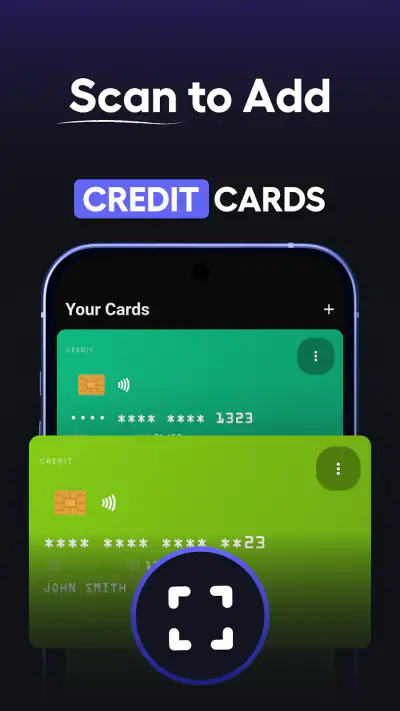
Not necessarily. The app may support cards that contain barcodes, QR codes, or other compatible details, but not every physical card can be imported automatically. Some cards may need to be added manually, scanned with the camera, or created from information supplied by the card issuer. Compatibility can also depend on the retailer, country, barcode format, and current app capabilities.
Does Wallet - Digital Card Wallet work without an internet connection?
Many digital cards can usually be displayed offline once they have been saved on the device, which is useful when shopping in places with weak reception. However, certain functions may require an internet connection, including synchronizing data, downloading updated passes, signing in, or receiving changes from a card provider. It is sensible to open the required card before leaving home if offline access is important.
Can I transfer my cards when changing phones?
Transfer options depend on how Wallet - Digital Card Wallet stores and synchronizes your information. If the app offers an account, cloud backup, or export feature, your cards may be recoverable after signing in on another device. Without synchronization, you might need to add them again manually. Before deleting the app or replacing your phone, check the backup settings and keep important physical cards available.














